The Midterms, the Market, and What We’re Watching
A Democratic takeover of Congress could create challenges for certain industries, but history gives us no reason to assume it would derail the stock market. In fact, some of the strongest historical results have come with a Republican president and a divided government.
That matters as investors look ahead to November’s midterm elections.
Washington can make life harder for individual businesses while the broader market continues to rise. The question is how the election could affect company profits, taxes, and the outlook for businesses we own.
What history tells us
Since 1950, the S&P 500 has finished higher in the 12 months following every midterm election through 2022, with an average price gain of approximately 15%. That measures the year following Election Day, rather than the next calendar year, and excludes dividends. (am.jpmorgan.com)
That is a strong record. It is also a historical pattern, not a promise.
Midterm years themselves have often been more difficult. Capital Group’s research shows that from 1931 through 2025, the S&P 500 averaged a 4.7% price return in midterm years, compared with 9.5% in other years. Volatility has also tended to be higher during midterm years. (capitalgroup.com)
One possible explanation is straightforward: Before the vote, investors face uncertainty. Afterward, they have a clearer picture of what Washington can get done.
But an election does not erase inflation, lower interest rates overnight, or fix an overpriced stock. We still have to do the work.
A Republican President and a Democratic Congress
Some investors assume that a Democratic victory under a Republican president would hurt stocks. The historical results challenge that assumption.
Barron’s cites the following average S&P 500 returns in the 12 months following midterm elections, using data going back to 1930:
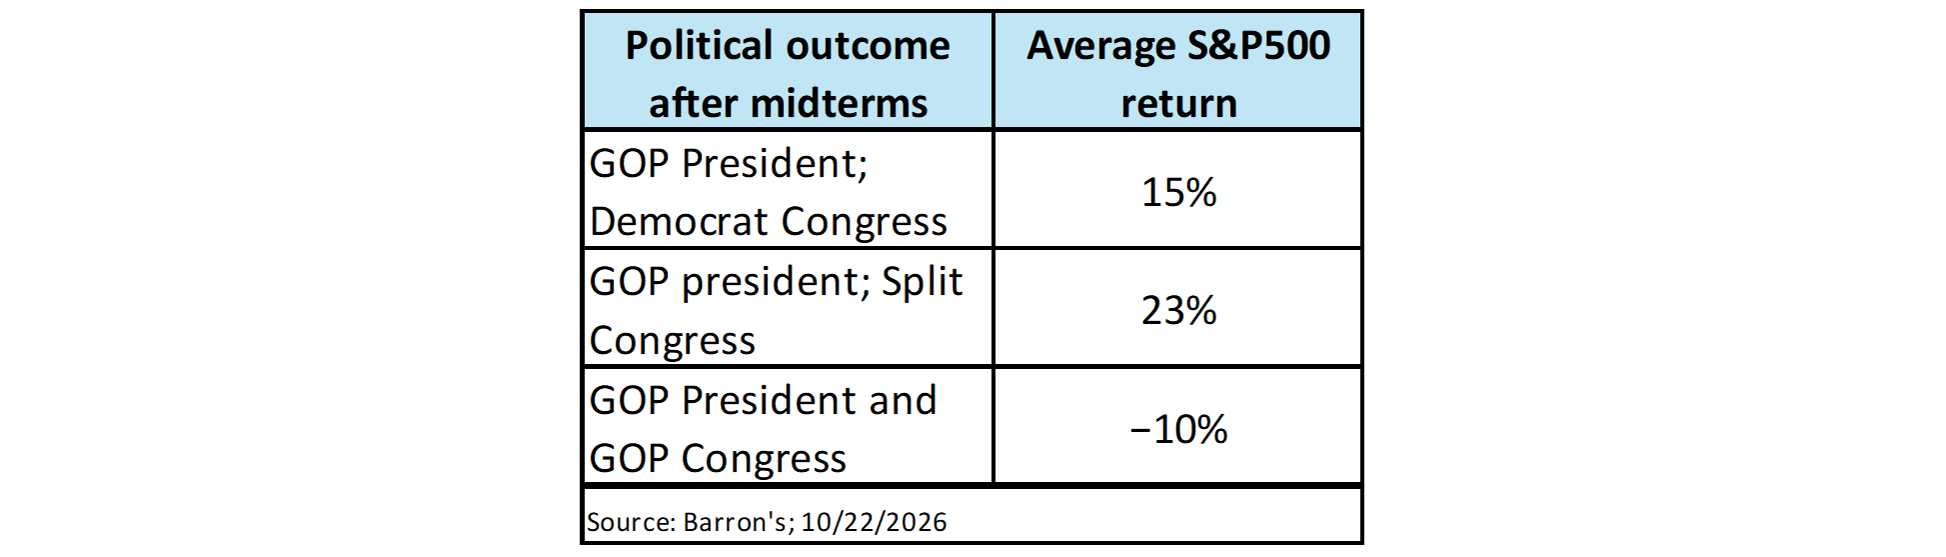
These are historical averages, not forecasts.
Why might divided government help? Our view is that businesses can benefit when neither party has a free hand to make sweeping changes. Political gridlock can make major changes to taxes, spending, and business rules harder to pass.
However, we would be careful about drawing too much from these averages. Each category contains a limited number of elections. Recessions, interest rates, valuations, and earnings all influence the results. This comparison also begins in 1930, a different period from the post-1950 record discussed above.
The lesson is simple: One party controlling Washington does not guarantee better investment returns.
What changes if Democrats take Congress?
Winning either chamber would give Democrats the ability to block legislation and control that chamber’s committees. Winning both would increase their leverage. President Trump would still hold the veto pen.
We would expect more investigations, tougher negotiations, and a harder path for additional Republican legislation. A wholesale reversal of existing policy would be much more difficult, particularly because many administration priorities operate through executive actions and federal agencies. (morganstanley.com)
That leaves several areas worth watching.
Artificial intelligence and data centers. Projects need electricity, water, land, and local approval. Political resistance can slow construction or increase costs. Morgan Stanley expects substantial AI investment to continue, but increasingly with conditions attached. Many decisions sit with governors, utility commissions, and local governments, making state elections important, too. (morganstanley.com)
Our concern is the gap between what investors expect and what companies can deliver. If a stock’s price assumes rapid growth, even a delay can hurt. A company can have a bright future and still be priced too high.
Healthcare. Drugmakers and insurers could face greater scrutiny over pricing and business practices. But the effects would vary. Hospitals could benefit if negotiations soften scheduled Medicaid cuts or support insurance coverage. We would examine the individual business rather than assume every healthcare company faces the same outcome. (barrons.com, morganstanley.com)
Crypto and financial services. Greater congressional scrutiny could complicate expectations for lighter regulation. We would be careful with investments whose appeal depends heavily on favorable treatment from Washington. (barrons.com)
Government funding and debt negotiations. Divided government can restrain sweeping policy changes. It can also make necessary agreements harder to reach. Budget and debt ceiling disputes could create uncertainty for stocks and bonds, even if the eventual agreement produces little lasting policy change. (morganstanley.com)
How we approach the election
We see no sound reason to make an all-or-nothing market call based on which party wins Congress.
We do see a reason to examine what we own:
- How much growth is already built into the stock price?
- Could a policy change reduce company profits?
- Are too many holdings exposed to the same risk?
- Do we have enough liquidity to avoid selling during a difficult market?
Those questions lead to better investment decisions than trying to predict the market from an election result alone.
At Palumbo Wealth Management, we will assess the outcome through its effect on earnings, taxes, business conditions, and valuations. We will have a clear opinion, and we will change it when the facts warrant it.
The historical record after midterms is encouraging. The risks to individual companies are real. Our job is to weigh both and act accordingly.
Historical performance does not guarantee future results. Historical averages reflect different economic conditions and limited samples. Investing involves risk, including loss of principal. This commentary is for informational purposes and is not an individualized investment recommendation.
Have a great week!
What We’re Reading
-
Chevron and Exxon hit all-time highs as refining profits soar in reaction to Iran and Ukraine wars
-
Nasdaq falls more than 2% as investors rotate out of tech after Amazon, Intel earnings
-
CNBC’s full interview with former NEC Director Gary Cohn (video – 17 Minutes)
Palumbo Wealth Management (PWM) is a registered investment advisor. Advisory services are only offered to clients or prospective clients where PWM and its representatives are properly licensed or exempt from licensure. For additional information, please visit our website at www.palumbowm.com.
The information provided is for educational and informational purposes only and does not constitute investment advice and it should not be relied on as such. It should not be considered a solicitation to buy or an offer to sell a security. It does not take into account any investor’s particular investment objectives, strategies, tax status, or investment horizon. You should consult your attorney or tax advisor.
The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward‐looking statements. Please note that any such statements are not guarantees of any future performance and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
All information has been obtained from sources believed to be dependable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability, or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
All information has been obtained from sources believed to be dependable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability, or completeness of, nor liability for, decisions based on such information, and it should not be relied on as such.
The views expressed in this commentary are subject to change based on the market and other conditions. These documents may contain certain statements that may be deemed forward‐looking statements. Please note that no such statements are guarantees of any future performance, and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
Past performance is no guarantee of future returns.
AI, Earnings Season, election cycles, government debt, Healthcare, Midterms, Split Congress
By: Adam
