Strong Expected Q3 Earnings On Deck
The past few weeks have not been pleasant, but a respite may be coming. Roughly 44% of S&P 500 companies are scheduled to report earnings next week, and a strong quarter is expected. While consensus expectations are setting a very high bar at 27% earnings growth, historical trends favor another aggregate beat, as actual earnings growth has consistently outpaced Wall Street estimates over the last few years. Could a stock rally follow?
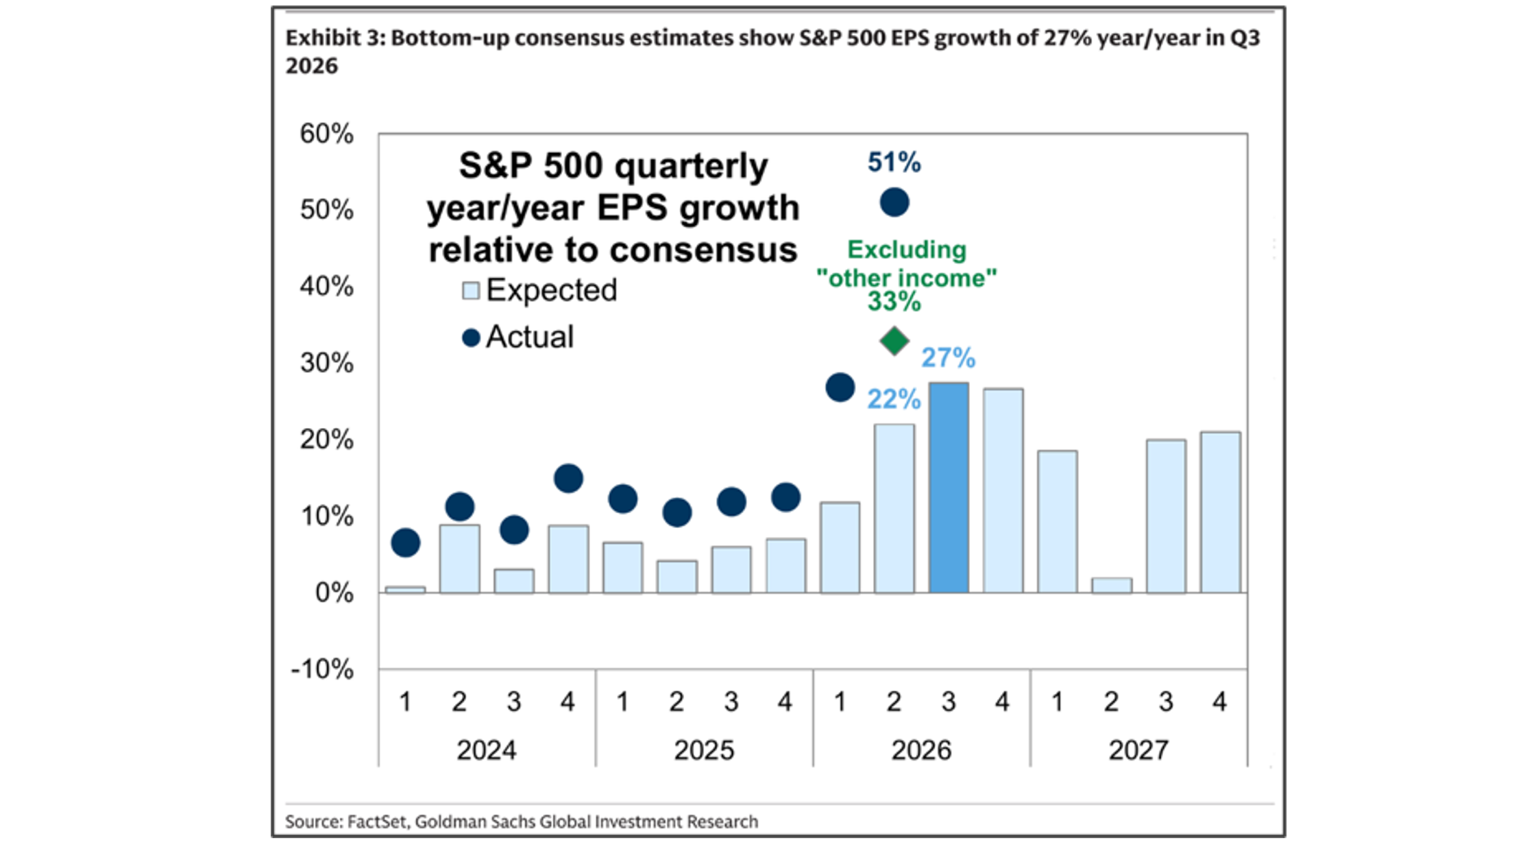
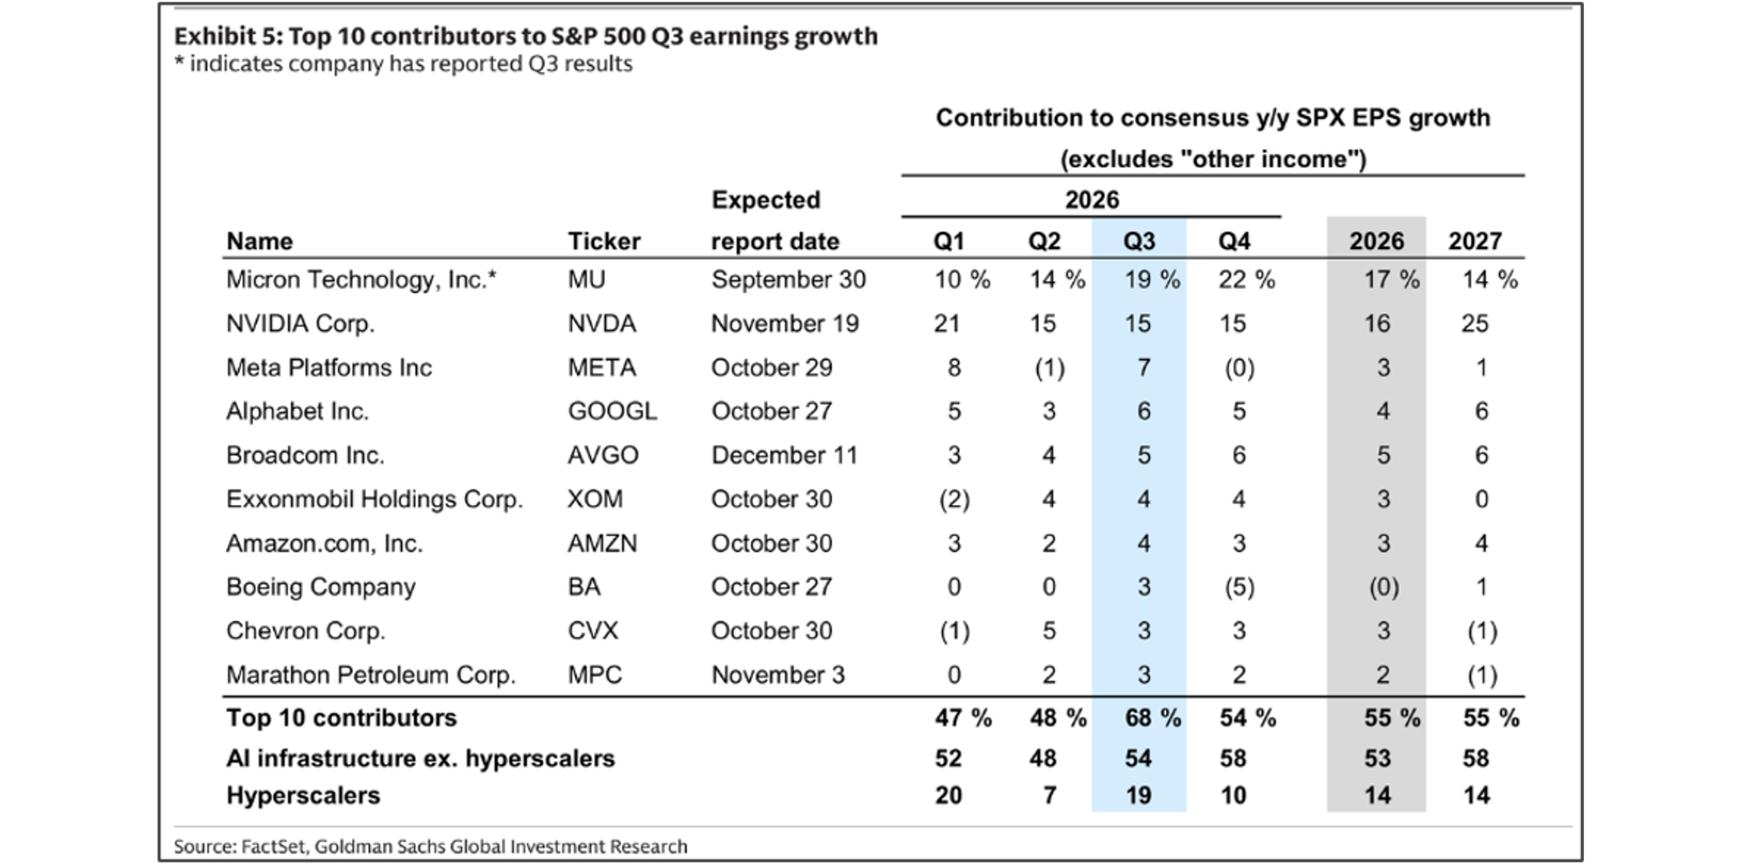
Whether reality can beat these high expectations relies on a relatively small group of companies. Expected earnings growth this quarter is highly concentrated, with the top 10 contributors expected to account for 68% of the total earnings growth for the entire S&P 500 (see chart below, blue shading). The other 490 companies in the index are expected to contribute just 32% of total growth, which is slightly LESS than the 34% combined earnings contribution coming from just two companies: Micron (MU) and NVIDIA (NVDA).
Room for a Rally?
Despite the choppy market action we have witnessed lately, this setup could actually pave the way for a year-end rally.
- Strong earnings: Even if concentrated, strong earnings reports are rarely associated with weak markets.
- Buybacks: As earnings are reported, the window for buybacks re-opens and the end of the year is typically the strongest seasonal period for buybacks. The hyperscalers won’t be buying nearly as much as previously, but the rest of the market is primed and ready to go, particularly financials.
- Positioning: The last month has seen a de-risking of intuitional exposure to technology. As a result, positioning is far from extreme and valuations have come down during the recent choppy market.
- Interest Rates: Yes, rates have been rising and there is fundamental pressure for higher rates, but that is currently being trumped by European sovereign debt issues, which is creating demand for U.S. treasuries and moving rates down. The U.S. is not in great shape, but it is better than France or Germany.
However, this potential year-end run is not without risk. The primary threat to market sentiment stems from the private markets and the pending Anthropic IPO. Frontier models like Anthropic and OpenAI are facing strong competitive headwinds from open-source alternatives, which is creating questions around Anthropic’s proposed $2 trillion valuation.
If the public market forces a reduction in this valuation, it could trigger a negative carry-over effect across the entire AI ecosystem. In the worst-case scenario, if Anthropic is unable or unwilling to complete its IPO, it could raise deeper structural questions about the AI trade and offset the near-term tailwinds.
The stage is set. The show is about to begin. Grab a chair and watch as earnings reports unfold next week. Have a great week!
What We’re Reading
-
Fewer people are flying as airfare soars.
-
Housing is flashing warning signs just as the Fed weighs more interest rate hikes
-
U.S. budget deficit swells to almost $2 trillion for fiscal 2026, up 12% in a single year
-
The Hidden $40-Per-Barrel Cost Driving Oil Prices Higher
Palumbo Wealth Management (PWM) is a registered investment advisor. Advisory services are only offered to clients or prospective clients where PWM and its representatives are properly licensed or exempt from licensure. For additional information, please visit our website at www.palumbowm.com.
The information provided is for educational and informational purposes only and does not constitute investment advice and it should not be relied on as such. It should not be considered a solicitation to buy or an offer to sell a security. It does not take into account any investor’s particular investment objectives, strategies, tax status, or investment horizon. You should consult your attorney or tax advisor.
The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward‐looking statements. Please note that any such statements are not guarantees of any future performance and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
All information has been obtained from sources believed to be dependable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability, or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
All information has been obtained from sources believed to be dependable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability, or completeness of, nor liability for, decisions based on such information, and it should not be relied on as such.
The views expressed in this commentary are subject to change based on the market and other conditions. These documents may contain certain statements that may be deemed forward‐looking statements. Please note that no such statements are guarantees of any future performance, and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
Past performance is no guarantee of future returns.
AI Bubble, AI buildout, AI capex, ai data centers, Anthropic, buybacks, Earnings Growth, Earnings Season
By: Adam
